Tuesday, August 05, 2025
The SAVE Trap: Why Doing Nothing Could Cost You Thousands
You ever think doing nothing is the safe move?
Yeah, not this time.
If you're sitting pretty in that SAVE payment pause thinking you're beating the system, spoiler alert...you’re not. In fact, your student loans might be growing faster than your houseplants when you forget to water them for a month.
Let me break it down real easy, especially for my people in their 20s, 30s, and early 40s, who are busy grinding at work, living life, and dodging Sallie Mae’s calls.
Here’s what really happens if you stay in the SAVE pause and what to do instead if you’re trying to retire before 80.
😱 1. Your Student Loan Balance Will Grow Like Mold in a Forgotten Tupperware
As of August 1, the Trump administration said, “Time’s up.” Interest is back.
That means every day you sit in SAVE forbearance without paying, your balance is ballooning.
💥 Let’s do the math:
If you owe $39,000 (the average federal loan balance), and your interest rate is 6.7%, you’re racking up about $219/month in interest alone.
That’s $2,628 a year.
Just… evaporating from your future.
🧠 Fun fact: That’s enough to buy Beyoncé floor seats. Twice.
So yeah, “waiting it out” might feel easy but it’s actually expensive.
⏳ 2. You’re Not Earning Any Credit Toward Forgiveness
You know what else you're giving up by chilling in SAVE?
📉 Progress toward loan forgiveness.
Every month you stay in that paused-forbearance limbo, you're missing out on credit toward Public Service Loan Forgiveness (PSLF) or Income-Driven Repayment forgiveness.
Those who switched repayment plans months ago?
They’re already 10 payments ahead of you.
🔥 Client Story:
Meanwhile, his friend? Still in SAVE. Still stuck. Still broke.My client Jay, a 29-year-old teacher, ditched SAVE back in March. He’s now 5 months into PSLF progress and saving $147/month on IBR.
🧨 3. You’re Getting Auto-Moved by 2028 Or Sooner
The government says you’ll be kicked out of SAVE and put into a new plan (RAP) by July 1, 2028.
But that’s just the latest date.
Experts expect it to happen much sooner likely within a year. And if you wait for them to switch you, you might get stuck in a plan that isn’t in your best interest.
You wouldn’t let your ex pick your next partner, right?
So why let the government pick your repayment plan?
✅ What To Do Instead
Look, SAVE was designed to help—but now it’s broken. It’s not your fault. But it is your responsibility.
Here’s your move:
🧭 Switch into a real Income-Driven Repayment (IDR) plan—like IBR (Income-Based Repayment).
Payments based on income
Credit toward forgiveness
Avoid growing interest
Keeps your options open
🎯 Final Word
This isn’t about scaring you it’s about waking you up.
You didn’t work this hard, get this degree, and rack up this debt just to let it grow like some evil Tamagotchi.
You’ve got dreams. You’ve got goals.
You’ve got bills that don’t need to be higher than they already are.
So stop waiting. Stop hoping they’ll fix it for you.
Take the wheel.
Hey, I'm Ivory.
Certified Financial Coach and Best Selling Author
I'm all about helping Millennials and Gen Z'ers crush their financial goals and live their best lives.
Join The Community:
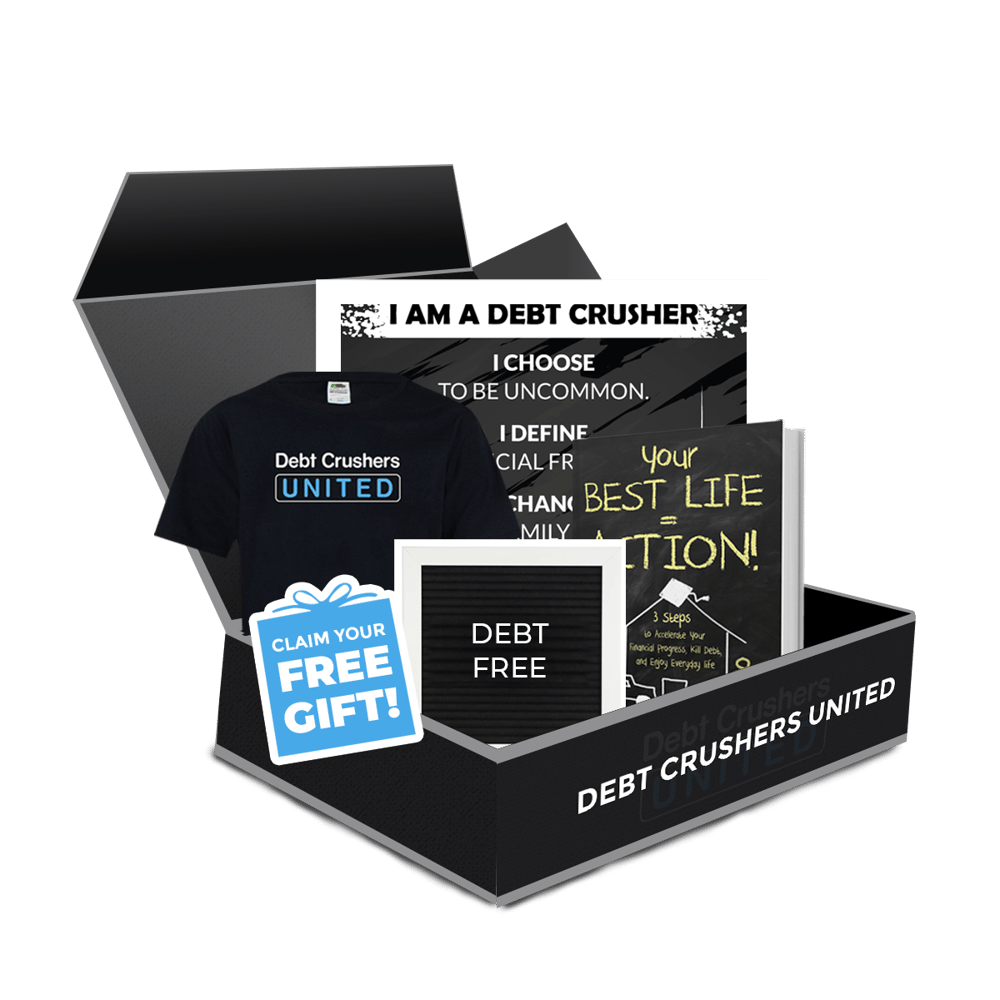
Have you claimed your FREE amazing welcome gifts yet?
...Test-drive the new 'Debt Crushers United' Club for 14 days, and we'll send you these gifts for FREE...
Exclusive For You
Apply for 1-on-1 Coaching With Ivory
***Private Coaching Is Limited To Only 5 People At A Time... Apply To See If Any Open Spots Are Available.
**WARNING (This aggressive approach is only for those who truly want to be debt free)
Debt Crushers United © 2025 - 2030 | All Rights Reserved | DebtCrushersUnited.com
Terms and Conditions | Privacy Policy | Member Login