Wednesday, January 07, 2026
The Story: Your Wallet vs Inflation
Ever feel like you’re working hard but your homeownership dream is still stuck in first gear? What if I told you that you can still buy a home in 2026, even if you’re carrying debt, battling rising grocery bills, and living through inflation? Keep reading, this is the game plan most financial blogs don’t give you.
Picture this:
It’s 2026. Groceries are expensive, your student loans didn’t take a holiday, and housing feels like an exclusive club where you forgot the password. I get it — I’ve sat across from clients who felt the same. One client — let’s call her Jenna — was juggling $25,000 in credit card and student debt while dreaming of her first home in Detroit. Most advisors told her to “wait until rates fall.” But waiting? That was just renting time instead of building equity.
Here’s the truth: mortgage rates have come down slightly from their peak, and while they’re still above where they used to be, experts expect them to hover around the 6% range in 2026, with conditions possibly easing affordability a bit more than 2025.
But rates aren’t your enemy — your DTI (debt-to-income) ratio is. And that’s something you can control.
What Lenders Really Look At
Lenders want to see two things when you apply for a mortgage:
1. Your credit score and employment stability
2. Your debt-to-income ratio (DTI) — that’s your monthly debt payments divided by your monthly income.
Here’s the deal:
Mortgage pros say the lower your DTI, the better your chances for approval and a lower interest rate. Ideally, lenders like to see your DTI below 36% — and the sweet spot for lowest rates is 25% or less.
That’s the key narrative arc here: win the DTI battle, win the mortgage race.
Your Roadmap to 2026 Homeownership
Think of this as your three-step leveling up process — simple, actionable, and real:
1. Crush High-Interest Debt First
Your credit card and personal loan payments are like leaks in a bucket — they drain your capacity to qualify for a mortgage. One of the fastest ways to improve your DTI? Pay off the highest interest debts first. That doesn’t just save you money — it frees up room in your budget.
Brookfield Residential
Funny fact: If grocery prices keep rising, at least your down payment savings grow thinner slower than your credit card balance grows due to 30%+ APR. 😅
2. Grow Your Income and Savings — Don’t Just Cut Back
Debt payoff isn’t only about austerity. Ask for that raise. Freelance on weekends. Put tax refunds and bonuses straight into debt or down payment savings. A little extra income shrinks your DTI fast.
3. Be Strategic With Your Money Before You Apply
Check your credit score now — and fix any errors. Don’t take on new debt (yes, that means hold off on that financed car or big electronics purchase). And yet — don’t just wait for interest rates to drop. Waiting can cost you rent increases and lost equity over time.
Jenna’s Win: A Real Success Story
Back to Jenna. She and I built a plan:
-Snowballed credit card debt first
-Added $150 extra monthly toward high-interest balances
-Boosted side hustle income by $600 per month
Three months later her DTI dipped below 30%. Six months later, she was pre-approved. Next year? Keys in hand.
Her story proves something crucial: You’re closer than you think.
The Big Picture for 2026
Here’s the market vibe for 2026:
-30-year mortgage rates are still elevated compared to historic lows — but more stable than recent years.
Experian
Home price growth nationally has slowed, and affordability is tickling better levels than in 2024 and 2025.
The MortgagePoint -
More homeowners with higher-rate mortgages may list their homes, increasing inventory and your opportunity to buy.
NAMP
So don’t let inflation stories and rising grocery bills become your excuse. Let them become your motivation.
Final Thoughts
You can buy a home in 2026.
You can pay down debt faster than you think.
You can lower your debt-to-income ratio and grade into better rates.
And most of all? You deserve a place to call your own — not your landlord’s.
Ready to make this your year? Let’s do it together. Drop a comment, share your debt number, and let’s build your plan.
Hey, I'm Ivory.
Certified Financial Coach and Best Selling Author
I'm all about helping Millennials and Gen Z'ers crush their financial goals and live their best lives.
Join The Community:
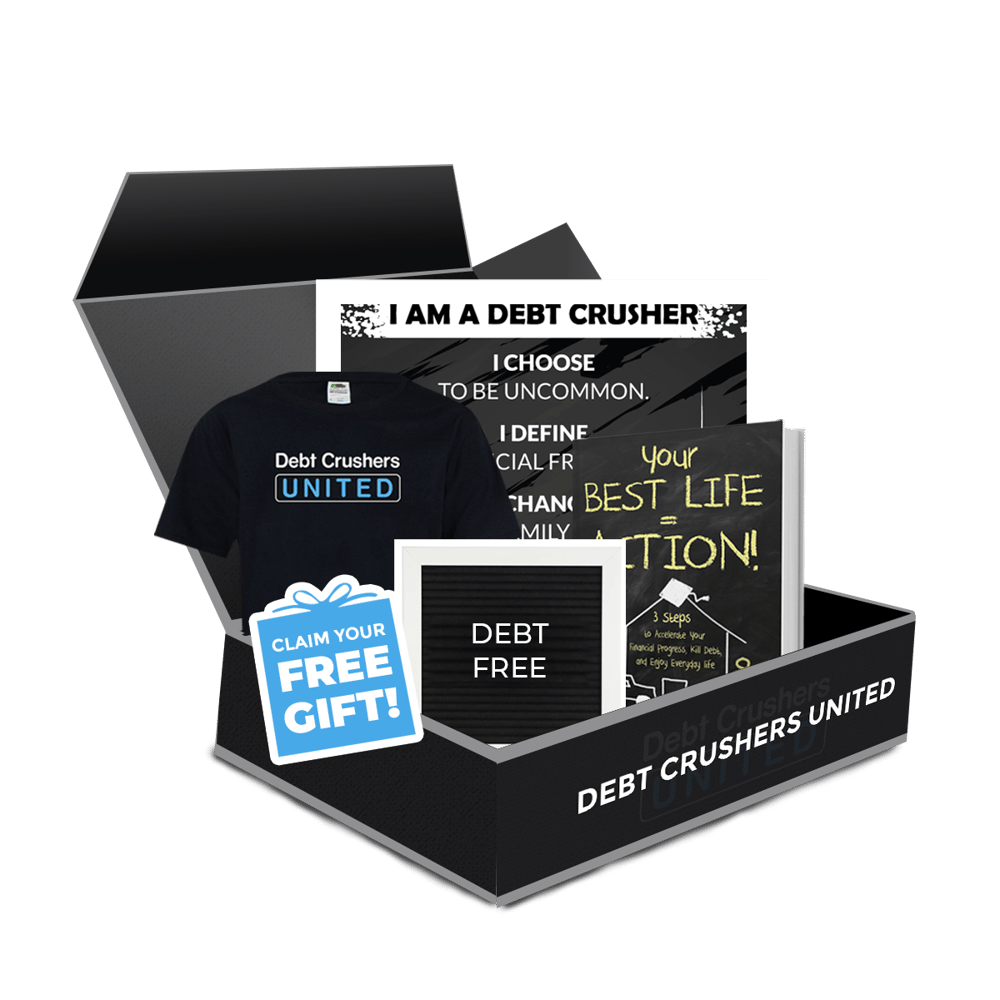
Have you claimed your FREE amazing welcome gifts yet?
...Test-drive the new 'Debt Crushers United' Club for 14 days, and we'll send you these gifts for FREE...
Exclusive For You
Apply for 1-on-1 Coaching With Ivory
***Private Coaching Is Limited To Only 5 People At A Time... Apply To See If Any Open Spots Are Available.
**WARNING (This aggressive approach is only for those who truly want to be debt free)
Debt Crushers United © 2025 - 2030 | All Rights Reserved | DebtCrushersUnited.com
Terms and Conditions | Privacy Policy | Member Login